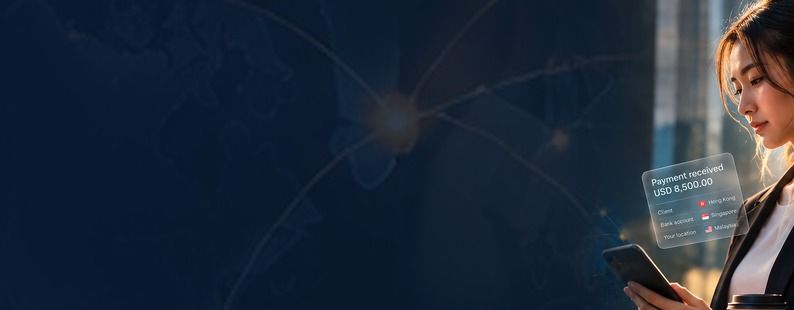
In today's borderless world, it is common to live in one country, work in another, have a client somewhere else, and receive payment into a different bank account.
So, where should you actually pay tax?
AT A GLANCE
It's Not Just About Where the Money Comes From
For personal service, freelance and contractor income, the key questions are usually where you are tax resident and where you physically perform the work. The location of your client or bank account does not necessarily determine where the income is taxable.
QUICK COMPARISON · SELECTED COUNTRIES · INDIVIDUAL SERVICE INCOME
If you are… / Country
Tax system
Income generated locally 1
Income generated overseas 1
General rules
Tax resident
🇸🇬 SG / 🇭🇰 HK
Mainly territorial
Generally taxed regardless where the payment received
Generally not taxed regardless where the payment received
Mainly follow where income is generated
Tax resident
🇲🇾 MY
Territorial + foreign-income rules
Generally taxed regardless where the payment received
– Generally taxed when received in MY, but qualifying foreign income may be exempt until 2036 2
– Generally not taxed when received overseas
Follow where income is generated first; if foreign income, check where received & exemption rules
Tax resident
🇦🇺 AU / 🇳🇿 NZ
Worldwide
Generally taxed regardless where the payment received
Generally taxed regardless where the payment received 3
Tax resident → generally worldwide income
US tax resident / US citizen
🇺🇸 US
Worldwide (residence + citizenship)
Generally taxed regardless where the payment received
Generally taxed regardless where the payment received
US citizen / tax resident → generally worldwide income; foreign tax credit may apply if foreign tax is paid
1 For service/freelance income, "where income is generated" generally follows where the person actually performs the work — not where the customer/payer is or where the bank account is.
2 Qualifying foreign income received in Malaysia may be exempt if the exemption conditions are met (e.g. the income was subject to tax overseas).
3 Certain AU temporary residents may be exempt from AU tax on some foreign income, and NZ new/returning tax residents may qualify for a temporary exemption on most foreign income for up to 4 years.
Please note: (a) This is a high-level learning table for individuals/service income only — it does not apply to dividends, interest, rent, capital gains, or companies. (b) Under CRS, overseas bank account information may be reported to your tax-resident country. Receiving money overseas does not change where you are tax resident or where income should be taxed.
THREE REAL-WORLD EXAMPLES
How Tax Jurisdiction Is Determined in Practice
Case 01
Malaysia Resident HK Client, Singapore Bank
You live and work in Malaysia, provide services to a Hong Kong client, and receive payment into a Singapore bank account.
📍 Live & work Malaysia
🤝 Client Hong Kong
🏦 Bank account Singapore
As a General Rule
Malaysia tax applies.
If you physically perform the work in Malaysia, the income is Malaysian-source — regardless of where the client is or where payment is received.
💡 Key takeaway
Follow where the work is performed — not where the money goes.
Case 02
NZ Tax Resident Temporarily Works in AU
You are a New Zealand tax resident, temporarily travel to Australia to perform freelance work. Your client is based in New Zealand.
🏠 Home residence New Zealand
✈️ Work location Australia (temp)
🤝 Client New Zealand
As a General Rule
Potentially both AU and NZ — but not necessarily double tax.
AU may have taxing rights as the work is performed there. NZ taxes residents on worldwide income. DTA or foreign tax credit rules may provide relief.
💡 Key takeaway
Worldwide-tax system: earning income overseas does not take it outside your home country's tax net.
Case 03
US Citizen Lives & Works in Singapore
You are a US citizen living and working in Singapore, earning income from work performed there.
🛂 Citizenship United States
📍 Live & work Singapore
💼 Income source Work in SG
As a General Rule
Singapore tax applies — and US tax rules still follow the US citizen.
The US taxes citizens worldwide even when living overseas. SG–US have no comprehensive DTA, but a Foreign Tax Credit (FTC) may be available for Singapore tax paid. The Foreign Earned Income Exclusion (FEIE) may also be relevant.
💡 Key takeaway
No DTA does not automatically mean double taxation — domestic FTC rules may provide relief.
DTA VS FOREIGN TAX CREDITS
DTA vs Foreign Tax Credits — What's the Difference?
Double Tax Agreement (DTA)
A treaty between two countries that determines how cross-border income is taxed. It may give one country primary taxing rights, provide an exemption, reduce a rate, or allow a credit, depending on the treaty.
DTA
Country A ↔ Country B
Agreement between countries
Foreign Tax Credit (FTC)
A credit for qualifying tax already paid to another country. Under many countries' domestic rules, an FTC may be available even where there is no comprehensive DTA with that other country.
FTC
Foreign tax paid → Tax credit
Relief under applicable domestic tax rules
Neither means you can simply choose the country with the lowest tax rate.
FOUR QUESTIONS TO START WITH
Four Questions to Start With
01
Where am I tax resident?
02
Where is the work performed?
03
Is there a DTA between the two countries?
04
Can a foreign tax credit reduce double taxation?
Cross-border taxation is nuanced. The same income can be treated very differently depending on where you are tax resident, where the work is performed, and which treaty rules apply.
DFG Advisory is an accounting, tax, advisory and fractional CFO firm with a strong focus on the fintech and technology sector, though we work across industries. Corporate advisory is our core strength, and where your personal tax situation intersects with business or cross-border complexity, we are happy to help you think it through.
This newsletter is for general informational purposes only and does not constitute tax advice. Tax rules vary by jurisdiction and individual circumstances. Always consult a qualified tax professional for advice specific to your situation.